Financial Literacy
4 Ways to Stay Financially Fit this Summer
Ahh…summer! The season of flip-flops and sunscreen, lemonade and baseball games. What’s not to love about summer?
Unfortunately, though, summer is also the season of overspending for many. When the sun is blazing across a cloudless sky and the day stretches on with endless possibilities, purse strings are looser and cards are swiped with abandon. But nothing kills summer fun like a busted budget and a mountain of debt. So, how can you stay financially fit this summer? Keeping your finances intact throughout the summer is well within reach if you’re ready to plan ahead and make responsible choices. Here are four hacks for a summer of financial fitness. If you’re a freelancer, business owner, or you get paid per diem, you can expect to see a drop in income during the summer months. Business is notoriously slower across a wide range of industries during the summer, so it’s best to be prepared for this reality. To avoid dipping into savings or going into debt, you can trim your discretionary spending and use the extra funds to cover non-discretionary expenses. You can also choose to find a side hustle for the summer to cover the gap in your income. Your budget will see some changes in the summertime, and it’s a good idea to prepare in advance instead of being caught unaware. Here are some changes you can anticipate: Aside from adjusting your monthly spending plan, you’ll want to build a workable budget for your summer getaway to avoid overspending. Money choices are nearly always better made in advance, so plan for every conceivable expense during your vacation. Attach a dollar amount for your hotel stay, car rental, food costs, transportation expenses, entertainment and outings, gifts, and any other cost you might have. Leave a bit of wiggle room for miscalculations, but try to keep your budget as close to the actual cost as possible. While on vacation, be careful not to go over budget and be open to a last-minute change of plans if some expenses end up being substantially higher than expected. Like going off a diet, blowing a budget is never an excuse to go all out and overspend without sparing a thought to the consequences. To avoid falling into this trap, resolve to review your budget and your overall spending on a regular basis throughout the summer. You can choose to do this weekly, or bi-weekly, but be sure to take a careful account of every dollar in and every dollar out. Being aware of the state of your finances in real-time instead of waking up after the damage has been done will make it easier to make responsible choices going forward. The temptation to overspend is especially strong during the summer. Follow these tips to keep your finances intact throughout the summer.
What is a Fraud Ring and How Can I Keep Myself Safe?
Q: I’ve been hearing a lot about fraud rings and how dangerous they can be for both businesses and consumers. What is a fraud ring, and how can I keep myself safe from falling victim?
A: A fraud ring is a group of fraudsters and merchants that can operate for years, stealing money and information while causing tremendous damages and loss.
Let’s take a deeper look at fraud rings, how they operate and how consumers and merchants can keep themselves safe. What is a fraud ring? A fraud ring is an organized circle of criminals that works to defraud and steal from people. They’ll use the same tactics as smaller groups of scammers and individual crooks, but they work on a much larger scale. They also tend to have access to more technology and resources than a scammer who is working alone. Consequently, the harm they can do is on a much larger scale as well. A fraud ring can consist of a group of criminals, as in any organized crime ring, or it can consist of a family of crooks working together to pull off their crimes. The members of the fraud ring collaborate to share information that can help them commit acts of fraud to net vast amounts of stolen funds and merchandise. Fraud rings take a tremendous amount of skill and coordination to create and run. Unfortunately, though, they can be very lucrative for fraudsters. In addition, the skill used to operate these rings makes them very difficult to detect and they can operate for years before being caught. The good news is that investigators can use their own advanced methods to identify and catch fraud rings and bring their operators to justice. How does a fraud ring operate? A fraud ring can operate under one of several pretexts. One common premise involves forgery, in which the fraud ring will create fake claims, steal identities and even print counterfeit checks and currency. Some rings target individuals, committing identity theft and the like, but many will focus on targeting eCommerce websites, businesses, charities, or government agencies. The fraud rings will often test their software against the business’s payment solutions by trying to make purchases through bogus giftcards or by using fake credit cards. If the fraud ring can get past the first line of defense the business has in place, it will move on to more severe crimes against the business, including larger purchases paid for via fraudulent means, hacking into the company’s database, and stealing the personal details of their customers and more. A fraud ring can commit any of the following scams: How can I recognize a fraud ring? Unfortunately, with the world of commerce and banking moving more online, fraud has become more rampant than ever. There are millions of pieces of sensitive data floating around the internet, including Social Security numbers, checking account information, credit card numbers and more. While most of this is inaccessible to the common crook and hidden behind safety measures like encryption, lots of data slips through cracks and gets picked up by scammers. There are also sophisticated hacking and phishing methods that help criminals gain access to this information. Finally, scammers can use a few bits of innocent, but identifying information, such as a date of birth, street address, and hometown — all of which can easily be found online and on social media accounts — to crack open passwords for accessing sensitive data. In fact, the internet has made fraud so rampant that research shows there is a new victim of identity theft every two seconds. Fraud rings have naturally also benefited from the massive amounts of information that can be scraped off the internet. With their increased manpower and resources, fraud rings can, unfortunately, access lots of data from individuals and merchants. Fortunately, you can learn to recognize signs of fraud and protect yourself from falling victim to a fraud ring or a scammer working alone. Look out for these red flags which can indicate signs of fraud: If you own a business, you may be at even greater risk of falling victim to a fraud ring. Be sure to look out for several sudden and large purchases from a customer who hasn’t made a purchase in a while, new accounts from customers that quickly become big spenders, and claims that demand refunds for faulty products you believe were in perfect order when shipped. It’s also important to follow rules of safe online interaction and identity protection at all times. Never share any sensitive information online or on the phone unless you are absolutely sure you are engaging with a reputable entity on the other end. Detecting instances of fraud at the first sign of suspicion can help mitigate the damage and keep your money and your information safe.
Step 6 of 12 to Financial Wellness: Pay it Forward
Now that you’ve started paying down debt, you and your partner have tackled big money issues, and you’ve mastered the art of spending mindfully, you’re now ready to think beyond your own needs by learning how to pay it forward. Money management can sometimes feel inherently selfish. You’re earning, budgeting, saving, and investing, all so you and those you love can enjoy a worry-free life on your own standards. But there is so much more you can do with the money you’ve been blessed with – as well as with your time, talents, and possessions. Let’s explore five different ways you can make the world a better place by paying it forward. The classic way to pay it forward can also be the simplest. Find a charity or two that speaks to your heart and make a donation that fits your budget. Ideally, it is substantial enough to make a difference, but any amount you are able to responsibly commit adds value and is appreciated. Be sure to verify the authenticity of the organization on a charity-vetting site like BBB Wise Giving Alliance, Charity Navigator, or CharityWatch. Don’t forget to save your receipt so you can claim a charitable-giving deduction on your taxes. Kindness doesn’t have to be big or loud to make a difference. It doesn’t even have to be costly. Small things that mean a lot can really make someone’s day. You can offer to make a coffee for your coworker, feed a parking meter that’s about to run out for a stranger’s car, remove a branch or rock from the middle of a busy thoroughfare or walking trail, or let someone go ahead of you at a checkout counter. There’s so much you can do when you look to give. When was the last time you thanked your child’s teacher for doing such a fantastic job on providing your child with an education? When was the last time you thanked your parents for giving you life, a happy childhood, and their ongoing love and support? When was the last time you thanked your mailperson? Pick up a nice set of thank you cards and spend 20 minutes writing thank you cards to the people in your life; those who do so much for you, but aren’t always thanked for everything they do. Your letters will likely be cherished by the recipients for many months to come. Unfortunately, there are numerous people in this world who are suffering from sickness, poverty, loneliness, mental health challenges, or other hardships. With just a small donation of your time, you can help alleviate some of their suffering. You can volunteer at a soup kitchen, help bring cheer to hospitals, offer to babysit for a couple who is going through hard times so they can have a night out to themselves, or make a habit out of visiting a lonely person. You can brighten someone’s day with your presence alone! Aside from money and time, there are so many ways you can use what you have to bring cheer into someone else’s life. You can donate old clothing to Goodwill or gift a friend or neighbor with a full set of your child’s outgrown clothing if it’s still in great condition. Offer to lend out your books to your bookworm friends. Run a low-cost, or even no-cost, yard sale for all the toys, furniture, and other items in your home that you don’t use any longer. Share your unused sports equipment with children who are less privileged than yours. There are so many ways to pay it forward and make the world a better place. And when you give to others, you’re really giving to yourself by learning how to be a better, kinder person.
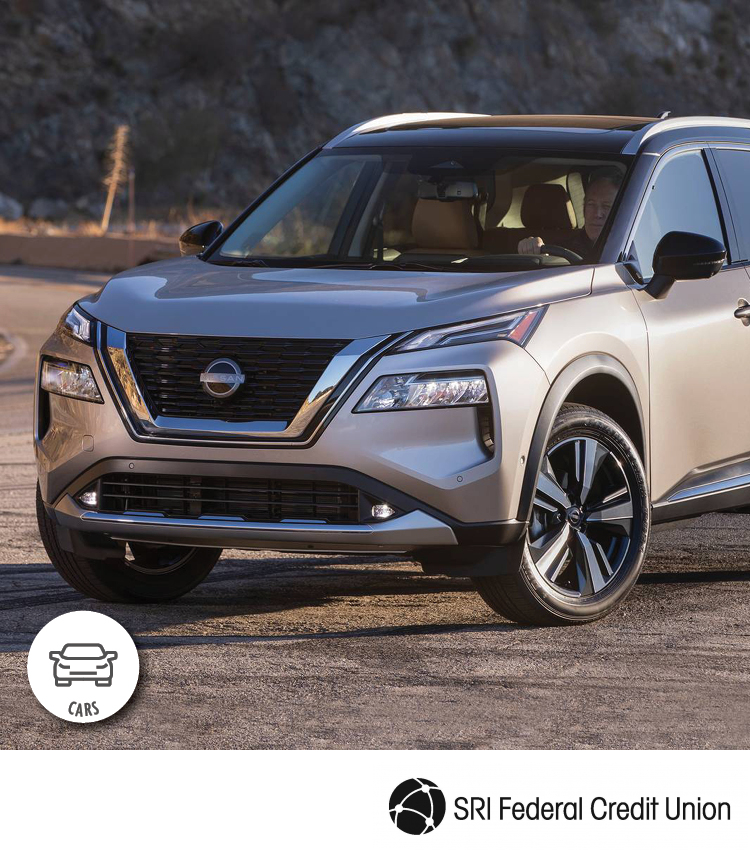
The Nissan Rogue – A Buyers Guide and Breakdown
The Nissan Rogue at a Glance:
- Vehicle type: AWD, FWD, 5-seater SUV
- Base price: $26,700
- Engine/transmission combo: 1.5 liter, VC-turbo, 3-cylinder direct engine hooked up to an Xtronic CVT
- Power: 201 horsepower @5,600 rpm
- EPA fuel economy: 30/37 mpg
Pros Cons Infotainment Safety features Interior Trim levels: If you’re looking to finance an auto loan for your new car, look no further than SRI Federal Credit Union! Our auto loans offer low-interest rates (click here for current rates), a choice of term lengths, and a quick approval process. Click here to apply or call 650-859-5477 to speak with a loan officer to get started or discuss available options!
How to Celebrate Memorial Day on a Budget
Celebrating Memorial Day can cost a pretty penny, but there’s no need to spend lavishly to have an epic holiday weekend. Here’s how to celebrate Memorial Day on a budget. 1. Hit the beach Get out to the shore at the first opportunity! The beach can provide hours of relaxation and fun for the entire family at little or no cost, depending on your location. Stock up on some inexpensive patriotic-patterned towels to make the day feel a little more festive. 2. Attend a local event There’s no need to travel far for a fun Memorial Day outing. Check out local online forums and newspapers to see what’s happening in your town. You’ll likely find a carnival, parade, concert and/or street fair that’ll give you some Memorial Day fun at no cost. As a bonus, local activities that do charge an entrance fee will often donate all proceeds to charity, so you’ll be paying it forward all day long. 3. Host a potluck If you’ll be hosting this Memorial Day, make it a potluck party. Ask each guest to bring one dish for a complete dinner that won’t cost anyone a lot of money. As a bonus, the menu is a lot more fun when it’s varied and prepared by lots of different cooks. 4. Go easy on the decor No need to blow a ton of money on making your Memorial Day celebration look festive. Spruce up the place with some red, white and blue balloons from the dollar store, find some patriotic banners and deck the tables with inexpensive and on-theme tablecloths, too. 5. Make a signature drink Instead of setting up a full bar, make one signature drink for the night. Festive and fitting for the celebration, this comes out a lot cheaper than springing for a full-blown bar. You can find some great ideas for your signature Memorial Day drink here. 6. Look for coupons Don’t go anywhere without first checking if you must pay full price. You can pick up some great discounts on restaurant meals, entertainment venues, and more at websites like Groupon.com. If you are a member of AARP or AAA, check to see if you can enjoy some additional exclusive discounts as well. 7. Host a DIY sports event For a fun and frugal alternative to the traditional Memorial Day BBQ, invite family and friends over to your place, or meet up at a park, for a day of sports and games. You can play flag football, soccer, have a tug-of-war competition or even drum up a full game of baseball. You can set up some light drinks and snacks, or ask your guests to bring their own for a truly cost-free day. 8. Visit historical sites What better way to spend Memorial Day than checking out historical attractions? Lots of historical sites, like the Gettysburg National Military Park in Pennsylvania, host free events in honor of the three-day holiday. This event, along with other similar events across the U.S., like the Annual Flag Planting Event at the San Francisco Presidio National Cemetery are a great way to honor the courageous men and women who have served and lost their lives for our country. 9. Rent a boat Enjoy a day out on the water at little cost by renting a boat from a nearby boat rental service or a private owner. Small boats, like kayaks and canoes, can cost as little as $30 for a few hours of use. Speed boats and pontoons will be pricier, but can also hold more people to share the cost. Bring along some snacks and drinks and good music for a fantastic day of water fun. 10. Participate in a race Joining a race can be an enjoyable and healthy way to spend your Memorial Day. Participating in a race can cost you as little as $50. As a bonus, lots of Memorial Day races donate all proceeds to organizations that help soldiers pay for expenses that are not covered under military benefits. You’ll be supporting our servicepeople while stretching those muscles! Memorial Day is always great fun, but it doesn’t need to cost a great deal of money. Use these tips to enjoy a memorable holiday weekend on a budget.
12 Steps to Financial Wellness-Step 4: Have the Money Talk with Your Partner
You’ve tracked your spending, created a budget, worked on ridding yourself of debt, and are well on your way to a financially secure life. Now you’re ready for step four, in which you’ll have the money talk with your partner. Talking finances with your partner may not be your idea of a shared romantic moment, but communicating openly about how you manage your money is a crucial part of having an honest and trusting relationship. It’s fairly common knowledge that arguing about money is the leading cause of divorce in the U.S., and no one wants to be the next statistic. Unfortunately, though, people often grow defensive when discussing the ways they choose to spend their money. How, then, can two partners have a calm, productive discussion about money? Here are six tips we’ve compiled to help guide you in this super-important conversation. It’s never a good idea to bring up a potentially explosive topic without warning. Instead, broach the topic to your partner a few days before you want to have the “Big Money Talk” and ask if you can have an open discussion about money sometime soon. This way, you’ll each have time to prepare the details you’d like to talk about, and you’ll both be ready to focus on the conversation without distractions. Instead of starting the conversation by bringing up a time your partner overspent or wondering aloud why your better half doesn’t seem to be saving enough for the future, start with a vision you can both share. For example, you can talk about how wonderful it would be to take a luxury vacation to the Cayman Islands, or how you’d love to start saving for a home. This way, you are communicating a shared dream and putting a positive spin on your money talk, which will set the tone for the rest of the conversation. You may be the more responsible, or the more detail-oriented partner, but it’s still important to listen carefully to what your partner has to say. Your partner will have their own ideas about money management, and you may be surprised at the insights they have to share into your own spending habits or expensive vices. At a certain point in your relationship, you may decide to share expenses, split them evenly and have each partner cover different expenses, and/or to pool your savings. Whether you’ve already reached that level with your partner or you plan to bring up the topic now, be sure to talk openly about the way you feel so you have a better chance of avoiding future resentment. For example, if you earn more than your partner, should you be splitting expenses evenly? Can one partner take additional financial responsibilities, such as paying the bills, in lieu of contributing an equal amount of income to the pot? If one partner goes over budget, will they be responsible for patching up the difference by contributing more money? All of these questions, and more, are important to discuss up front to help prevent future blowups and/or hurt feelings. At this time, consider linking one of your accounts or opening a shared account at SRI Federal Credit Union. We’ve got convenient checking and saving accounts to suit every preference. Just stop by and ask how we can help. Sharing expenses and a budget can be liberating in a partnership, but it can also feel constricting. Sometimes, you just want to splurge without having to explain the purchase to your partner. You may also want to spend money on a surprise gift for your partner without them knowing you’ve just dropped a large sum of money on an expensive purchase. Having a slush fund, or money set aside for your personal “just for fun” spending, can help you maintain a sense of independence and keep some of your purchases private. You can keep this fund in a separate checking account under your name at SRI Federal Credit Union. No, you don’t need to have the Big Money Talk every week, but it is a good idea to touch base about finances once a week, or once every two weeks. You can talk about recent purchases, big expenses that are coming up soon, surprise bills and more. Setting aside time to talk about money will keep the stressful money arguments out of your everyday conversations. You did it! You had the money talk with your partner, and you are closer than ever. Be sure to stick to your commitments and to bring up any money issues that may arise during your regular money talks for continued harmonious collaboration about all financial matters.
Step 3 of 12 to Financial Wellness: Pay Down Debt
You’ve tracked your spending, designed a budget for your monthly expenses, and you’re well on your way to financial wellness. In this next step, you’ll create a plan for paying down your existing debt. Consumer debt can be one of the biggest challenges to realizing good financial wellness. Credit card companies design their business model in a way that makes it easy to get stuck paying off debt for years. With some intentional action and commitment, reaching true financial wellness and being financially independent is possible. At the very least, seek to be on track for paying it off shortly. Below, we’ve outlined how to pay down debt in five simple steps, along with three debt-paying strategies to avoid. Before you get started, determine how much debt you must pay off. List every credit card you own that has an outstanding balance and jot down the amount owed to each. Next, list the interest rate of each card. Do this for any other fixed installment loan debt you have as well. These numbers will help you build a debt-payoff plan in the next two steps. You can also add up the amounts owed on each account to reach your total outstanding debt amount. There are two main approaches people utilize for getting rid of their debts: Each method has advantages and drawbacks. The snowball method provides frequent motivation as debts are paid off sooner, but it may involve paying more overall interest on the debt. The avalanche method, on the other hand, generally saves the borrower a significant amount they pay in interest, but it can take a while to generate results. Choose the method that makes the most sense for your personal and financial circumstances. Once you’ve chosen your debt-crushing method, it’s time to find ways to maximize your monthly credit card payments. You can do this by trimming your spending in one budget category and channeling that money toward paying down your debt. You can also find ways to pad your pocket with extra cash for your payments, such as freelancing for hire or selling your creations on a platform, like Etsy, if you’re the crafty type. Once you’ve determined how much you can afford to pay each month, you can create a debt-payoff plan using the systems you’ve reached in Step 1. For some consumers, the most challenging part of paying down debt is managing multiple payments across several credit card accounts. With several monthly debt payments to make, it can be complicated to remember them all. It can also feel like the monthly payments are only going toward interest. A debt consolidation loan can change all that. When you consolidate debts into one low-interest loan, it’s a lot easier to manage the monthly payments. Plus, the savings on interest payments can be significant, especially if the new loan has a low-interest rate. If this approach sounds favorable, consider taking out a personal loan from SRI Federal Credit Union. The loan will provide you with the funds you need to pay off your credit card bills and leave you with a single, low-interest monthly payment. Click HERE to apply for a personal loan or click HERE to read up on our Zero % Visa Balance transfer promo. Many credit card companies are willing to lower your interest rate once you prove you are serious about paying down debt. After kicking off your debt payment plan, it’s worthwhile to contact each credit card company to discuss your options. At the very least, see if you can get the company behind the first debt on your list to lower your rate. 3 Debt-Crushing strategies to avoid As you work toward paying down your debt, beware of these debt-crushing strategies, which may do more harm than good: Regardless of the strategy you choose, or the methods you use for paying off your debt, commit to not adding more charges onto your card while paying it down. Paying off a large amount of debt will take time and willpower, but living debt-free is key to financial wellness. Best of luck on your debt-crushing journey!
Last-Minute Tax Tips to Know Before You File
The big day is drawing near, and if you haven’t already done so, it’s time to file your tax return! Before you file, though, it’s a good idea to review your return to ensure you haven’t made any mistakes or forgotten any deductions or credits you’re eligible to claim. Below, we’ve compiled a list of last-minute tax tips to know before you file. Consider filing electronically If you still file your taxes the old-fashioned way, you may want to consider switching to e-filing this year. The IRS e-file is available to all taxpayers, and many can file electronically at no cost. Re-check your Social Security numbers Make sure every Social Security number on your return, including your own, your partner’s and each of your dependent’s, is listed correctly. Check that the SSNs related to claims for Child and Dependent Care Credit or Earned Income Tax Credit are accurate as well. Don’t forget any deductions Be sure you’ve taken every tax deduction that’s available to you before completing your return. Here are some of the deductions that many people often forget to claim: In the past, if anyone other than the student paid toward a student loan, there were no tax benefits. Now, however, any student who is not claimed as a dependent can qualify to deduct up to $2,500 in student loan interest, regardless of who has made the payment. Make sure to claim the full Child and Dependent Care Tax Credit A tax credit reduces your tax bill dollar for dollar, so it’s important to claim every credit that is owed to you. There were big changes to the Child and Dependent Care Credit this year, and it’s best to take full advantage of those changes. The American Rescue Plan, signed into law on March 11, 2021, increases the credit and makes it fully refundable, so taxpayers can receive the credit even if they don’t owe taxes. The new law also expands the eligibility requirements for taxpayers who can benefit from the credit’s highest rate. The changes to the Child and Dependent Care Credit that apply only for tax year 2021 include: Double-check your figures If you are filing a paper return, double-check that you have correctly calculated the refund or balance due. Run the numbers through a calculator again, and then again, to ensure you haven’t made any mistakes in your figures. Get your return in on time Tax day is usually on April 15. This year, the deadline has been postponed to April 18. If you know you won’t be ready to file on time, you’ll need to request an extension. It’s important to note, though, that an extension to file does not include an extension for payment. Be sure to pay up on time or you may face penalties. Don’t forget to sign your form Your tax return must be signed and dated in order to be filed. If you’re filing jointly, be sure to have your partner sign as well. Also, if you’ve hired someone to prepare your return, have the preparer sign the form and enter their Preparer Tax Identification Number (PTIN). It’s tax time! Use the tips outlined here to maximize your refund and ensure there are no mistakes on your tax return. Your Turn: Share your last-minute tax tips with us in the comments.
Step 2 of 12 to Financial Wellness: Creating a Budget
Now that you’ve tracked your spending and kept a careful record of where your money goes over the course of a month, you’re ready to move on to the next step of financial wellness: creating a budget. Budgets play a crucial role in promoting financial awareness, which then helps to facilitate more responsible money choices. This discipline will benefit you individually, as well as all who are part of your household. Let’s get started by taking a look at how to create a budget and review some popular budgeting systems and how they work. Create a budget in 5 easy steps Budgeting systems While every kind of budget involves tracking expenses and committing to a maximum spending amount each month, there is a wide range of budgeting systems to fit every kind of personality and money management style. The traditional budget doesn’t involve much more work than the steps described above. After working out a number for every expense category, you’ll simply need to track your spending throughout the month to ensure you’re sticking to the plan. You can use a spreadsheet for this purpose, or utilize one of the popular budgeting apps, like Mint or YNAB, and do it digitally. The money-envelope system works similarly. However, instead of simply committing to sticking to your spending amounts for each expense category, you’ll withdraw the amount you plan to spend on all non-fixed expenses in cash at the start of the month. Divide the cash into separate envelopes, using one for each of these expenses. Then, withdraw cash from the appropriate envelope when making a purchase in that category. There’s no way to blow your budget with this system; when the money in the “Dining out” envelope runs dry, that’s all for this month! The 50/30/20 budget is simpler but requires more discipline. Set aside 50 percent of your budget for your needs, 30 percent for wants, and the remaining 20 percent for savings. Of course, you’ll need to make sure your income and expenses will work with this kind of budget. Does 50 percent of your income cover your needs? If yes, this budget allows for more individual choices each month and less accounting and tracking of expenses. A well-designed budget can provide its creator with a sense of financial security and freedom. When you stick to a budget, you’ll always know you have enough to get through the month and save for the future. Start budgeting today!
How to Celebrate Valentine’s Day on a Budget
Love is in the air and the money is flowing like heart emojis. According to the National Retail Federation, the average American spends $221.34 on Valentine’s Day each year. That’s a lot of money to spend on a one-day celebration!
Lucky for you, there are ways to enjoy a romantic evening with your partner without going into debt. Here’s how: Work with a budget Instead of spending mindlessly and regretting it afterward, designate a budget for all your Valentine’s Day expenses, and be sure to stick to it. In addition to helping you keep costs under control, working out a budget in advance will allow you to choose how to spend your money. You may decide to spend more on a gift and less on dinner, or maybe you’d rather skip both of these and splurge on a fun activity instead. Best of all, a preplanned budget means there will be no regrets spoiling the memory of your special day. Shop smarter with a sales app Check out shopping apps, like ShopSavvy or PriceGrabber, to score deals on that dream Valentines’ Day gift. The apps help you compare prices at online and in-store retailers, locate coupons for items you’re searching for and even bring up cash-back options to put money back into your wallet. Why pay full price when you don’t have to? Save on flowers Did you know that Americans spend close to $2 billion on Valentine’s Day flowers each year? Save on those beautiful blossoms with these tips: Bring down your dinner costs Don’t break your budget on a romantic dinner for two. First, consider dining in. Yes, we know your kitchen table isn’t the hottest place in town, but you can find another area in your home and turn it into a special spot for a special meal. Consider laying down a blanket in front of the fireplace for a picnic-inspired experience, moving a small table into the living room or even setting up a cozy corner in a rarely used room in your home, such as a storage room or guest bedroom. Cook up a storm, or order in — you’ll still save on restaurant costs by forgoing beverages, gratuities and other add-ons you end up blowing money on when you eat out. If you or your loved one are really looking forward to dining out, make it less expensive by learning how to beat the psychological tricks that restaurateurs play on diners to get them to spend more: Make something homemade Make a special treat for your special someone. Check out our video HERE to see how easy it is to make chocolate-covered strawberries and pretzels. Celebrate late If you dare, postpone your Valentine’s Day celebrations by a day or two for steep savings on all related expenses. You’ll find Valentine’s Day candy and greeting cards on clearance, gifts already marked down, and you won’t have to pay inflated restaurant prices for the same meal. Use these hacks to plan the perfect Valentine’s Day on a budget.